

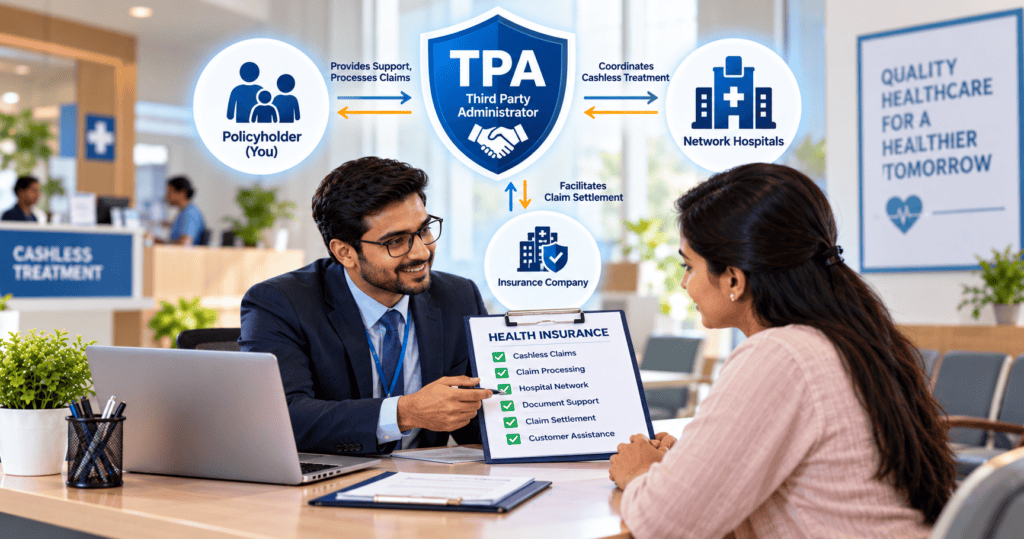
In India, health insurance has evolved significantly, getting more systematic and readily accessible. The Third Party Administrator (TPA) serves as one of the key components supporting this framework. Despite the fact that policyholders frequently interact with TPAs during claims, most are unaware of their specific role. Policyholders may avoid needless misunderstanding during medical crises and manage the claims standard procedure more effectively if they are informed about their role.
This page describes the role of TPA in health insurance in India, along with their duties, benefits, drawbacks, and effects on your overall insurance service. It also aims to clear up common misconceptions and offer relevant data to assist policyholders in making wise choices.
What is a TPA in Health Insurance?
A Third-Party Administrator (TPA) is an organisation licensed by the Insurance Regulatory and Development Authority of India (IRDAI) to assist insurance companies in managing health insurance services.
TPAs act as intermediaries between:
- The insurance firm
- The policyholder
- Healthcare establishments and providers
They carry out a vital operational role in managing claims. It also offers policyholder services, but they do not offer insurance products or set premiums.
The Reasons for TPAs in Health Insurance
Before TPAs were introduced, insurers handled all administrative and claims-related work internally. As the number of policyholders grew, managing hospital networks, claims, and customer service became complex.
The role of TPA in health insurance emerged to
- Boost the effectiveness of handling claims.
- Improve client service.
- Build hospital networks for cashless treatment.
- Standardise documentation and processes.
Important Purposes: TPA’s Function in Health Insurance
TPA plays a number of crucial roles in health insurance that have an immediate impact on policyholders.
Processing of Claims
1. Claims Processing
TPAs are responsible for:
- Verifying claim documents
- Assessing eligibility under policy terms
- Coordinating with insurance firms and clinics
- Accepting or rejecting claims according to insurer standards.
They handle both:
2. Cashless Hospitalisation Services
Facilitating cashless treatment is one of the most obvious facets of TPA’s function in health insurance.
How it operates:
- Policyholder visits a network hospital.
- TPA verifies policy details
- Pre-authorisation is approved
- Treatment proceeds without upfront payment (except exclusions)
3. Hospital Network Management
A network of hospitals where policyholders can get cashless care is maintained and expanded by TPAs.
Among their duties are:
- Empanelling hospitals
- Negotiating treatment costs
- Ensuring service quality
- Monitoring hospital practices
4. Customer Support and Assistance
TPAs act as the first point of contact for:
- Policy queries
- Claim status updates
- Documentation requirements
- Hospital guidance
This makes the role of TPA in health insurance essential for improving customer experience.
5. Documentation and Record Keeping
TPAs maintain:
- Policyholder data
- Medical records (for claims)
- Claim history
Accurate documentation ensures transparency and speeds up the payment of claims.
6. Pre-approval and Confirmation
Before approving cashless treatment, TPAs:
- Check policy validity
- Verify coverage limits
- Confirm exclusions
- Approve treatment estimates
To be able to avoid fraud and ensure compliance, such an action is necessary.
7. Risk management and fraud detection
Finding questionable claims is another crucial function of TPA in the health insurance industry.
They:
- Analyse claim patterns
- Verify hospital bills
- Detect inflated charges or unnecessary procedures.
Types of Claims Handled by TPAs
TPAs manage different types of claims depending on the mode of treatment and hospital selection.
Cashless Claims
This type of claim allows policyholders to receive treatment without making upfront payments, subject to policy terms.
- Treatment at network hospitals
- TPA directly settles bills with the hospital.
Reimbursement Claims
These claims are applicable when treatment is taken outside the insurer’s network of hospitals.
- Treatment at non-network hospitals
- Policyholder pays first and later submits a claim.
In both cases, the role of TPA in health insurance remains central to processing and verification.
How TPAs Work: Step-by-Step Process
Understanding the process helps policyholders know what to expect during both planned and emergency hospitalisations.
For Cashless Claims:
This process is followed when treatment is taken at a network hospital with prior approval.
- Visit a network hospital.
- Submit a health card.
- The hospital sends a pre-authorisation request.
- TPA reviews and approves
- Treatment begins
- Final bill settled by TPA (as per policy)
For Reimbursement Claims:
This process applies when treatment is taken at a non-network hospital or without prior approval.
- Pay hospital bills
- Collect documents
- Submit claim to TPA
- TPA verifies documents
- Reimbursement of the claim amount (if authorised)
The Indian Regulatory Framework
The Insurance Regulatory and Development Authority of India (IRDAI) oversees TPAs in India.
Important rules:
- Required licensing
- Capital requirements
- Data confidentiality standards
- Defined scope of operations
TPAs cannot:
- Issue policies
- Reject claims independently without insurer approval.
- Alter policy terms
Advantages of TPAs for Policyholders
The role of TPA in health insurance offers several benefits:
1. Faster Claim Processing
Processing cycles are cut by dedicated teams. They avoid errors and delays by following standard operating rules. This is very helpful in critical situations where quick permissions are required.
2. Cashless Treatment Access
Wide hospital networks make treatment more convenient. Policyholders can access medical care without arranging immediate funds. This reduces financial stress at the time of hospitalisation.
3. Expert Support
Provides guidance regarding how to submit claim requests and what documents are necessary. TPAs help clarify documentation requirements and submission processes. This reduces the chances of claim rejection due to incomplete or incorrect paperwork.
4. Lower Operational Workload
Policyholders do not need to coordinate directly with insurers. TPAs handle communication between hospitals and insurance companies. This simplifies the overall process and saves time for policyholders.
Limitations and Challenges of TPAs
While useful, TPAs also have limitations.
1. Interaction Problems
Coordination among the medical facility, TPA, and insurer may at times lead to delays. In critical circumstances, having more parties involved could result in slower response times. Miscommunication or lack of timely updates may also affect the overall claim experience.
2. Limited Decision Authority
Final claim approval lies with the insurer, not the TPA. This can result in additional processing time as approvals may require insurer intervention. Policyholders may need to follow up with both the TPA and insurer for updates.
3. Variability in Service Quality
Different TPAs may provide varying levels of service. The efficiency and responsiveness can depend on the TPA assigned by the insurer. This may lead to inconsistent experiences across different policyholders.
4. Documentation Delays
Incomplete documents can slow down claim processing. The due date for resolution may be stretched by additional requests for paperwork. To avoid such delays, it is essential to provide complete and precise data.
TPA vs In-House Claim Settlement
Some insurers now manage claims internally instead of using TPAs.
| Aspect | TPA Model | In-House Model |
| Claim Handling | External TPA | Insurer directly |
| Speed | Moderate | Often faster |
| Control | Shared | Full control by the insurer |
| Customer Interaction | Via TPA | Direct |
Even with in-house models, the role of TPA in health insurance remains relevant for many insurers in India.
How to Check Your TPA Details
Policyholders can find their TPA details in the following:
- Policy document
- Health insurance card
- Insurer’s website
In an emergency, knowing your TPA is helpful. It provides faster coordination while a patient is in the hospital and minimises claim processing delays.
Tips for Policyholders
To make the most of the role of TPA in health insurance:
- Always carry your health card.
- For cashless benefits, pick network hospitals.
- Inform TPA before planned hospitalisation.
- Keep all documents safe.
- Follow claim procedures carefully.
A more seamless and effective claims process can be ensured by being vigilant and knowledgeable.
Typical Myths Regarding TPAs
Policyholders may become confused due to several misconceptions regarding the operation of TPAs.
1. TPAs Approve Claims Independently
They process claims, but final approval lies with the insurer. TPAs mainly assess and forward claims based on policy terms rather than making final decisions.
2. TPAs Decide Policy Terms
Policy terms are defined by the insurance company. TPAs only implement these terms during claim processing and do not have the authority to modify them.
3. TPAs Delay Claims Intentionally
Delays are often due to documentation or verification requirements. In many cases, additional checks are necessary to ensure compliance with policy conditions and prevent errors.
Future of TPAs in India
The role of TPA in health insurance is evolving with technology.
Emerging trends:
- Digital claim processing
- AI-based fraud detection
- Faster approvals
- Improved customer interfaces
Some insurers are reducing reliance on TPAs, but they still remain important for operational efficiency.
Conclusion
The efficient operation of India’s claims and service ecosystem depends on the role of TPA in health insurance. TPAs allow cashless hospitalisation, claim authentication, and customer support by operating as a link between insurers, medical facilities, and policyholders. Their involvement increases overall access to healthcare services funded by insurance and enhances operational efficiency.
It is equally important for policyholders to understand, though, that TPAs operate within guidelines defined by regulators and insurers. Knowing how TPA operates in health insurance can help individuals manage claims more effectively, avoid delays, and make wise choices while seeking medical care authorised by their insurance.
Frequently Asked Questions
Q1. What is the main role of a TPA in health insurance?
TPA’s role in health insurance is to help insurers with quality customer service, hospital coordination, and claims processing. They don’t sell insurance or set premiums; instead, they serve as middlemen. Additionally, they facilitate communication between all parties, which improves the efficiency of the claims process.
Q2. Can a TPA reject my health insurance claim?
TPAs assess and process claims, but the final decision is made by the insurance company. They may recommend rejection based on policy terms and documentation. The insurer reviews the TPA’s assessment before making the final decision on approval or rejection.
Q3. Is it mandatory to use a network hospital for claims?
No, but using a network hospital allows cashless treatment. Otherwise, you must opt for reimbursement, where the role of TPA in health insurance involves processing your claim after submission. Choosing a network hospital can simplify the process and reduce the need for upfront payments.
Q4. How long does a TPA take to process claims?
Timelines differ based on verification and documentation. According to IRDAI criteria, claims are typically processed in a few days to a few weeks. If more information or clarification is needed during the review process, delays could happen.
Q5. Can I contact the insurer directly instead of the TPA?
You can get in touch with the insurer, yes. However, TPAs are typically the main point of contact for claims and support because their job in health insurance is to manage operational responsibilities. In complicated situations, questions or problems may need to be resolved by both the insurer and the TPA.