

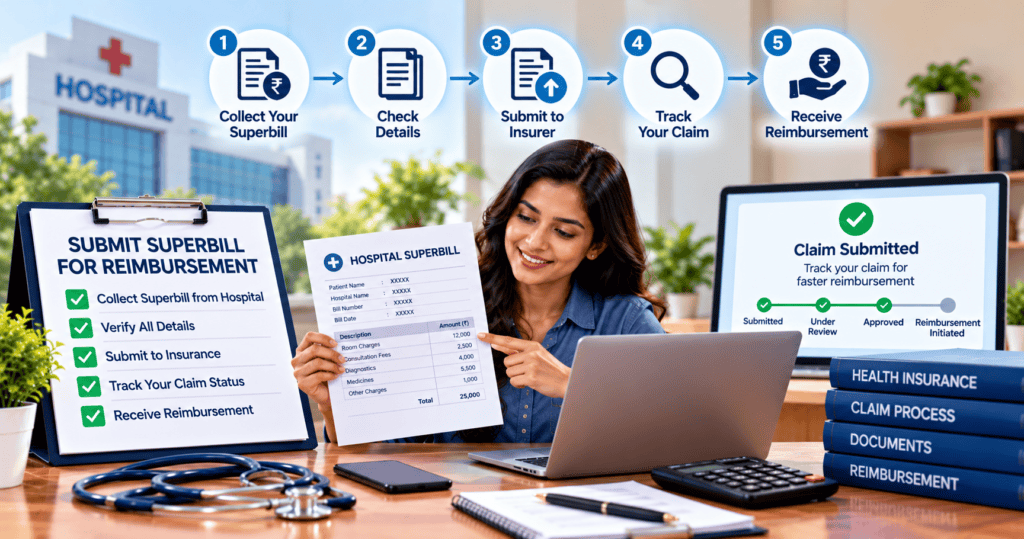
If you are trying to understand how to submit a superbill to insurance, it usually means your claim is not being handled directly by the hospital. You have already paid for the treatment, and now you need to submit the documents yourself to get reimbursed.
Now, this process is common when you visit a doctor or clinic outside your insurer’s network. Unlike cashless claims, where the hospital and insurer coordinate, reimbursement claims require you to submit proof of treatment, payment, and medical necessity.
The confusion usually comes from one point: what exactly should be submitted, and how do you ensure the insurer processes it without delays? Well, to answer that properly, you first need to understand what a superbill is and how it fits into the claim process.
What Is a Superbill?
A superbill is a detailed medical document prepared by your healthcare provider that explains your treatment in a format insurer can review. It is not just a payment receipt. There is a clear difference, you see, a regular bill only shows how much you paid, whereas a Superbill explains:- What treatment was provided?
- Why was it required (medical reason)?
- Who provided the treatment?
- How are the charges structured?
Components of a Superbill
Before you move ahead with how to submit a superbill to insurance, take a moment to check whether the document you received is actually complete. Many claim delays do not happen during submission; they happen because the superbill itself is missing important details. A standard superbill usually includes:- Patient details: Your name should match your insurance records.
- Provider details: Doctor’s name and clinic or hospital information.
- Date of service: When the consultation or treatment happened.
- Diagnosis details: Why did you visit the doctor?
- Treatment details: What was done during the visit.
- Itemised charges: A clear breakdown of costs, not just one total amount.
How Does a Superbill Work?
Unlike cashless claims — where the hospital coordinates directly with the insurer — reimbursement claims place the documentation burden on you; understanding insurance claims, how they work and why they matter is useful context before you start. There are two ways insurance claims are handled:- Cashless claim: The hospital sends bills directly to the insurer.
- Reimbursement claim: You pay first and submit documents later.
- You receive treatment at a non-network provider.
- You pay the full amount yourself.
- The provider gives you a superbill.
- You submit the superbill along with other documents.
- The insurer reviews the claim.
- The approved amount is reimbursed to you.
How to Submit a Superbill to Insurance for Faster Reimbursement
Now that the basics are clear, let’s go step by step through how to submit a superbill to insurance in a way that reduces delays.Step 1: Start With Policy Verification
Before preparing documents, check your policy carefully. You need to confirm:- Whether reimbursement claims are allowed.
- Whether your treatment is covered.
- Any limits such as co-pay, sub-limits, or exclusions.
Step 2: Validate the Superbill Before Submission
Errors at this stage are among the common mistakes while filling reimbursement claim forms catching them here avoids them compounding further down the process. You need to look for:- Correct patient name
- Clear treatment description
- Proper date and provider details
- Itemized charges
Step 3: Prepare a Complete Claim File
If the treatment was at an out-of-network provider, it helps to first understand what a TPA is and why IRDAI’s new rules matter for your cashless health insurance claim because the same third-party administrator handles reimbursement files too.- Payment receipt
- Prescription or doctor’s notes
- Diagnostic reports
- Discharge summary (if hospitalised)
- Policy details
Step 4: Fill the Claim Form With Matching Information
The claim form connects your documents to your insurance policy. While filling it:- Use the same name format as your policy.
- Match treatment dates exactly with the superbill.
- Copy provider details accurately.
Step 5: Submit Through the Correct Method
Now you know how to submit a superbill to insurance. However, here’s another consideration that comes into play. You see, the submission methods vary by insurer. You may need to:- Upload documents online
- Email scanned copies
- Submit physical documents
- Accepted file formats
- Whether original documents are required
- The submission timelines
Step 6: Track and Follow Up
After submission, your role is not finished. You should:- Save your claim reference number
- Track claim status regularly
- Follow up if there is no update
- Policy coverage
- Treatment eligibility
- Document completeness
- Approve the claim
- Partially approve it
- Ask for additional documents
Extra Tips to Speed Up Reimbursement
If your goal is faster processing, focus seriously on execution.- Submit all documents together, not separately.
- Ensure all files are clear and readable.
- Keep names and dates consistent.
- Use the insurer’s preferred submission method.
- Respond to queries without delay.
Common Mistakes That Slow or Block Payment
Most issues in reimbursement claims are not complex; they are small mistakes. Common ones include:- Missing documents
- Incorrect details in the claim form
- Unclear billing or treatment description
- Late submission
How to Read and Understand an Insurer’s Payment Calculation
If you are on a family floater plan, understanding how sub-limits apply across family members helps explain why the reimbursed amount may differ from what each individual paid. Here is why:- Policies include limits and sub-limits.
- Some expenses are not covered.
- Co-pay or deductible may apply.
Conclusion
Understanding how to submit a superbill to insurance is mainly about following the process correctly and ensuring your documents are complete. When you:- Verify your policy
- Submit accurate documents
- Track your claim
Frequently Asked Questions
Q1. Should I check my policy first?
Yes. Just make sure your treatment is covered. If it’s not, the claim won’t go through.
Q2. Can I submit only the superbill?
No. You’ll need receipts and reports, too. Otherwise, they’ll ask for them later.
Q3. What if something is missing in the superbill?
Fix it before submitting. It’s easier now than dealing with delays later.
Q4. How do I know what’s happening with my claim?
You’ll get a claim number. Use that to check the status online or call them.
Q5. Why didn’t I get the full amount back?
Some charges may not be covered, or there could be limits in your policy.