

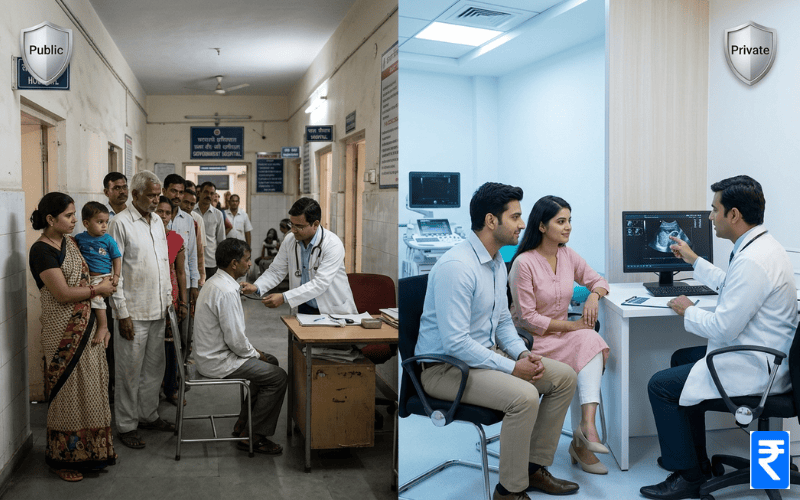
Care costs in India have skyrocketed over the last 10 years. Hospital stays, surgeries, medicines etc can all give financial pressure on families. Therefore, many people and households have been seeking health insurance as a financial safety net to protect themselves from sudden medical expenses.
Many types of health insurance are available in India. But at the highest level, they can be divided into two:
- National Health Insurance
- Private Health Insurance
Here you will see a complete rundown of these two approaches, what they are, how different their two-way maps are, advantages and limitations, costs and coverage patterns, eligibility criteria, and deciding factors.
The goal is to give you factual and balanced information so you can make your choices carefully.
Table of Contents
- What Is National Health Insurance?
- Major Government Schemes in India
- Objective of Public Health Coverage
- What Is Private Health Insurance?
- Key Features of Private Insurance
- Role of IRDAI
- Key Differences Between National and Private Health Insurance
- Funding and Cost
- Coverage Scope
- Network and Hospital Choice
- Flexibility and Customization
- Waiting Periods and Claims Process
- Advantages of National Health Insurance
- Disadvantages of National Health Insurance
- Advantages of Private Health Insurance
- Limitations of Private Health Insurance
- Which Option Is Best for You?
- Financial Capacity
- Healthcare Needs
- Age and Health Condition
- Risk Tolerance and Lifestyle
- Summing Up / Conclusion
- FAQs
What Is National Health Insurance?
National health insurance is a term mainly used for healthcare coverage that is government-financed, administered, or subsidized. In India, the government runs schemes to expand health coverage and provide financial protection. These programs focus especially on poor and vulnerable groups. These schemes aim to reduce people’s reliance on direct payments for health services. This helps lower the risk of catastrophic medical expenses.
Some of the major national health insurance programs in India that could be cited are the following:
- Rashtriya Swasthya Bima Yojana (RSBY): This is a government-sponsored program that mainly focuses on helping low-income families and workers of the unorganised sector by offering them cashless hospitalization benefits up to a certain limit per family.
- Ayushman Bharat, Pradhan Mantri Jan Arogya Yojana (PM, JAY): This is the main instrument for universal health coverage. It offers an extensive range of healthcare benefits, including secondary and tertiary hospitalization services to the eligible individuals and households.
State-level schemes that provide subsidized health coverage for eligible citizens.
These programs form part of the government’s overall pledge to achieve Universal Health Coverage (UHC) and guarantee that citizens will have access to essential healthcare services without suffering from financial difficulties.
What Is Private Health Insurance?
Private health insurance is a kind of health insurance that insurance companies in the private sector offer. Individuals or families purchase these plans by paying a yearly or monthly premium. Unlike national health insurance, private health insurance plans usually provide a wider range of coverage options and more flexibility.
Common features of private health insurance include:
- Individual or family health plans
- Coverage for hospitalization and medical procedures
- Optional benefits such as maternity care, critical illness coverage or outpatient care
- Choice of different coverage limits and deductibles
Private insurance plans are controlled by the Insurance Regulatory and Development Authority of India (IRDAI). It makes rules to protect people who buy insurance. It also makes sure companies clearly tell all important details and have enough money to pay claims.
Key Differences Between National Health Insurance and Private Health Insurance
Understanding the differences between the two systems can help you find which type of coverage you will need:
Funding and Cost to Policyholders
National Health Insurance: Usually a government program, it is financed through taxes, budgetary allocations, and grants. Those who qualify for the program may avail themselves of the coverage at very minimal or even no direct premium expense.
Private Health Insurance: Private plans need policyholders to pay premiums. The amount depends on age, health status, coverage level and add-on benefits.
Coverage Scope
National Health Insurance: Redirects to basic hospitalisation, essential treatments, and financial protection against major health risks. Initiatives like PM and JAY are examples that offer considerable coverage limits. On the other hand, specialized care, outpatient treatments, and wellness services are generally more restricted.
Private Health Insurance: Probably offers more comprehensive coverage, including not only hospitalization but also pre- and post-hospitalization expenses, maternity benefits, OPD coverage, mental health care, and critical illness benefits if selected.
Network and Hospital Choice
National Health Insurance: Often limited to government hospitals or network hospitals empaneled under the government programme. Demand can result in longer wait times.
Private Health Insurance: Usually allows patients the privilege of receiving medical care from an extensive network of private hospitals, including high-end facilities, which generally give the advantage of faster service and a wider choice of doctors.
Flexibility and Customization
National Health Insurance: Less freedom in customizing coverage. The benefits are determined by the objectives of the scheme and the eligibility criteria.
Private Health Insurance: People can customize their plans using various add-ons. These add-ons can be adjusted to match their health needs or personal preferences.
Waiting Periods and Claims Experience
National Health Insurance: The process can be slow because a public body handles claims. It often involves some paperwork.
Private Health Insurance: Usually upholds the process of claims settlement to be fast, provides online policy management, and supports the customer services to be very efficient if all the required documents are available.
Advantages of National Health Insurance
- Greater Access to Basic Healthcare: One of the primary goals of national health insurance programs is to make sure that healthcare services reach people who might otherwise struggle to get treatment.
- Lower Direct Costs: Various national schemes offer very low or even zero premium payments. This helps families avoid financial burden.
- Public Health Coverage: Since the national health insurance programs work at a national or state level, they can support large populations and help to give access to essential medical services.
Disadvantages of National Health Insurance
- Narrow Scope of the Plan: National health insurance does not cover certain services. You cannot use it for outpatient care, dental treatments, or advanced therapies unless they are specifically included.
- Hospital Capacity Constraints: The government hospitals operate under limitations of space and high patient numbers, so help over a period will usually take longer than if you turned to private care.
- Eligibility Restrictions: Some national programs help only specific groups, such as BPL families. Individuals can access benefits only if they meet the eligibility criteria.
Advantages of Private Health Insurance
- Wide and Adaptable Coverage: Private health insurance policies can include a wide range of medical services depending on the plan.
- Choice of Services: Policyholders can often choose their preferred hospitals, doctors, and treatments, giving more control over care decisions.
- Faster and Personalized Service: For many private policies, customer support, claims processing, and cashless service options are typically faster and more standardized.
Limitations of Private Health Insurance
- Higher Premium Costs: While comprehensive coverage is a good thing, the cost of premiums for adults or people with existing medical conditions can be high-risk.
- Exclusions and Limits: Many private policies exclude certain types of treatments, have lower benefit limits, or require a waiting period, especially for pre-existing illnesses.
- Renewability and Age Factors: As policyholders age, their premiums often rise. Coverage may shrink, and policy terms can become more restrictive.
Which Option Is Best for You?
There is no single answer that fits all situations. Your decision between national health insurance and private health insurance should factor in:
- Financial Capacity
If you are financially limited and struggle to pay premiums, then national health insurance schemes will offer basic protection at a lower cost.
- Healthcare Needs
In case you are expecting to need advanced care, frequent outpatient services, or specialist treatments, then private health insurance can provide you with a wider and more flexible coverage.
- Age and Health Condition
People who are young and healthy may opt for a combination of basic public coverage and an affordable private top-up plan.
- Risk Tolerance and Lifestyle
Individuals who want comprehensive, personalized plans with extra benefits may go for private coverage, whereas risk-averse individuals who focus on essential protection may prefer national schemes.
Summing Up
Healthcare expenses can give you a lot of financial stress. Health insurance helps you to reduce this risk by covering a portion of medical costs.
National health insurance programs in India focus on providing essential healthcare services to eligible citizens. This is given especially to those from economically vulnerable groups. These programs aim to improve access to hospital treatment and reduce high expenses.
Private health insurance plans give you broader coverage options and greater flexibility. However, they need premium payments. It can also include waiting periods or other exclusions.
When choosing options, you should consider many factors. It can be healthcare needs, financial capacity, hospital access, risks etc. Carefully checking the policy details and understanding eligibility requirements can help you choose the coverage option that supports all your healthcare needs.
FAQs
1. What is national health insurance in India?
National health insurance is basically a collective term for the health coverage programmes that health departments run. They are aimed at providing the citizens, especially the vulnerable groups, with a financial safety net against medical treatment costs.
2. How does private health insurance differ from national health insurance?
Private health insurance is a product that individuals purchase from commercial insurers. Its coverage is generally wider and can be customized to match their requirements. On the other hand, national health insurance is government-sponsored. It covers only a limited set of essential health services with little room for personal choice.
3. Can I have both national and private health insurance?
Yes. Most people rely on national health insurance to cover their basic needs, and they get private health insurance as a top-up to enjoy overall coverage plus any benefits that are outside the scope of public health schemes.
4. Are private health insurance premiums tax-deductible?
Yes. Section 80D of the Income Tax Act provides for deductions in respect of the amount paid towards the acquisition of health insurance for the individual as well as the family, subject to the specified limits.
5. Do national health insurance schemes provide cashless treatment?
Yes. There are a few national health insurance schemes, such as RSBY, PM, and JAY, that facilitate cashless treatment at empaneled hospitals if you comply with the other scheme conditions.