

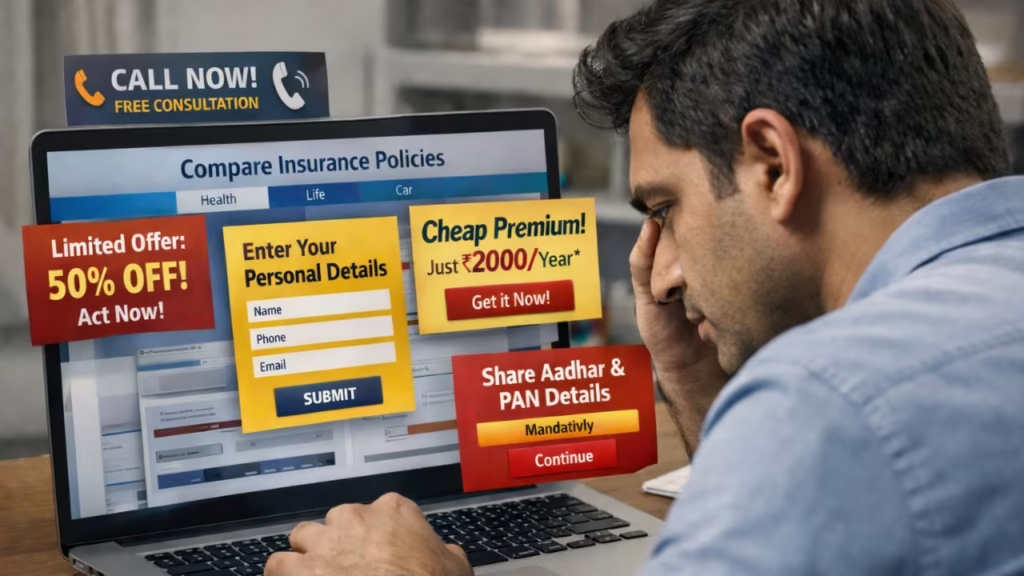
In a press release issued on 2 April 2026, the IRDAI highlighted the need for regulated insurance entities to comply with the Guidelines on Prevention and Regulation of Dark Patterns (as issued by the Central Consumer Protection Authority or CCPA), especially if they provide products on e-platforms. The industry regulator has also roped in the Institute of Public Auditors of India to monitor dark patterns and conduct a nine-month independent audit.
The move, aimed at mitigating dark practices such as forced data collection, hidden fees, and mis-selling, is in line with a broader regulatory push across the entire financial sector in India. Regulated insurance entities were also directed to carry out a self-assessment and submit their findings within 15 days of the publication of the press release. An action plan with a specific timeline to tackle and remove any existing dark patterns needed to be submitted as well.
The Survey That Opened a Can of Worms
Dark patterns have been escalating in the insurance industry since products moved to digital channels. Under stringent regulatory oversight, the IRDAI action targets manipulative design features in insurance apps or online sales processes that directly or indirectly coerce consumers into making financial decisions that benefit the insurer.
The directive follows a Local Circles survey of more than 87,000 insurance customers across more than 340 districts in India. The survey revealed alarming figures and deteriorating consumer trust:
- 85% claimed they were indirectly or directly forced to share personal information with insurers
- 80% reported obstacles when attempting to cancel existing policies
- 90% reported facing frequent calls, SMS, and emails after they attempted cancellation
- 82% reported mis-selling, stating discrepancies between advertised and actual terms weren’t uncommon
Also Read: How To File a Complaint With IRDAI
Dark Patterns Raising Concerns
The CCPA’s guidelines list around 13 dark patterns, among which the following are most common:
- False Urgency: Signifying false scarcity or popularity of a product to push sales figures
- Confirm Shaming: Evoking shame, fear or guilt in consumers to coerce them into keeping subscriptions or buying products
- Forced Action: Pushing users to buy products, sign up for emails, and share personal data for the benefit of the company
- Interface Interference: Planning and designing page interface to highlight or hide important consumer information for the benefit of the company
- Drip Pricing: Revealing hidden fees toward the later stages of transaction
- Disguised Ads: Misrepresenting advertisements as testimonials or user-generated content
- Malware: Inducing stress among consumers by making them believe their device is compromised to trigger payments
Emphasising the need for an independent audit, Ajay Seth, the IRDAI Chairman, stated at a public awareness initiative, “From the authority, when we sent a letter to all of you to check up on dark patterns, almost all have said they do not have dark patterns. With that kind of response, we have reached out to the Institute of Public Auditors of India to take up the study and also monitor, over a period of nine months, who has got dark patterns and who hasn’t”.
The Rights a Buyer Gains
While insurers are likely to face short-term inconveniences, tough enforcement will improve consumer confidence and benefit the industry in the long term. Online insurance buyers can expect more transparency in pricing and terms, low cancellation friction or privacy traps, and ease of policy management. Turning off auto-renewal features is expected to get easier, along with fewer unwanted calls or communication from the insurance company.
In the latest churn of events in the industry, the regulatory body has also slapped Canara HSBC Life with a penalty of ₹1 Crore for mis-selling insurance to an 88-year-old. Deficiencies and lapses in the sales process have been flagged. Consumers can avoid such risks by informing themselves adequately about various types of insurance products and standard grievance mechanisms. MyRupia focuses on that last bit. Get detailed guidance on life insurance policies or get to know your policy better through an independent expert.
Disclaimer: This MyRupia article is for informational purposes only and is based on publicly available government, regulatory and industry sources. It should not be treated as investment, financial, tax, insurance, or legal advice. Information, examples, market data, and expert views mentioned in the article may change over time and should not be considered a recommendation to buy, sell, invest in, or surrender any financial product. Readers should evaluate their individual circumstances and consult a qualified financial professional before making decisions.