

India’s insurance regulator plans to cap commissions and tighten expense limits to reduce policy costs and prevent mis-selling, while insurers and distributors seek clarity on implementation timelines.
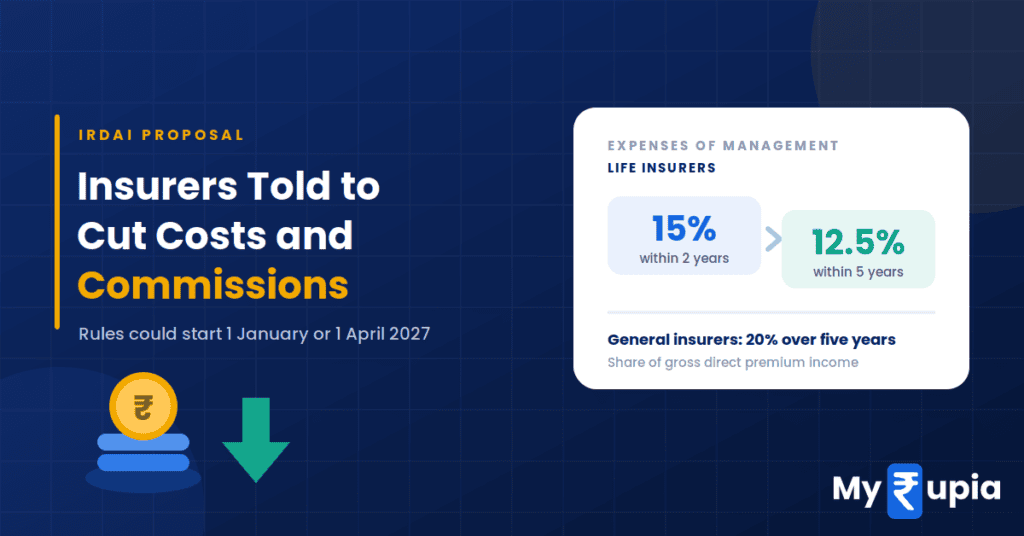
India’s insurance regulator, the Insurance Regulatory and Development Authority of India (IRDAI), plans to introduce tighter commission rules without disrupting the insurance market. Chairman Ajay Seth said the proposed reforms could take effect on 1 January or 1 April 2027, depending on industry feedback.
IRDAI introduced the proposals in September 2026 to reduce insurance distribution costs, improve transparency and protect policyholders against mis-selling. However, distributors and industry analysts warn that lower commission limits could affect existing business models, slow insurance sales and threaten jobs.
IRDAI seeks lower insurance costs
The proposed reforms would change how insurers compensate agents, brokers and other intermediaries. IRDAI aims to link insurance commissions more closely to factors such as product type, distribution channel, policy size and the effort required to sell and service policies.
The regulator has also proposed reducing expenses of management (EoM) limits over time. Under the draft framework, life insurers would need to bring EoM down to 15% of gross direct premium income within two years and 12.5% within five years. General insurers would face a gradual reduction to 20% over five years.
Additional measures include greater disclosure of commission structures, restrictions on sales incentives linked to volume and rewards, and a ban on compulsory insurance bundling with loans. These proposals aim to improve accountability and ensure customers receive better value from their insurance policies.
Insurers and distributors seek flexibility
Seth said he had met insurers and distributors to discuss their concerns. Industry participants requested greater flexibility for smaller companies and low-value insurance policies, along with sufficient time to adapt their operations.
Some stakeholders fear that lower payouts could weaken the incentive for agents and banks to distribute insurance products, particularly in segments that depend heavily on intermediary networks. Banks and other distributors may also need to reassess their revenue models if commission income falls.
However, IRDAI has indicated that it intends to address these concerns through consultation while maintaining the broader direction of its proposed reforms.
Final insurance rules await consultation
IRDAI will consider industry feedback before issuing draft regulations, which will give stakeholders another opportunity to comment. The regulator has identified 1 January and 1 April 2027 as possible implementation dates.
The final rules will determine how insurers and distributors adjust commission structures, manage operating expenses and maintain insurance sales. The changes could reshape India’s insurance distribution landscape as the regulator seeks to balance market growth, affordability and stronger policyholder protection.
How Insurance Works in India: Understand how insurance works, including policy terms, coverage and the claims process. Learn How Insurance Works
Also Read: Supreme Court Orders Travel Insurance for Offline Rail Tickets
Disclaimer: This MyRupia article provides information based on publicly available government, regulatory and industry sources. It does not constitute investment, financial, tax, insurance or legal advice. Information, examples, market data and expert views may change over time and do not represent a recommendation to buy, sell, invest in or surrender any financial product. Readers should consider their individual circumstances and consult a qualified financial professional before making financial decisions.