

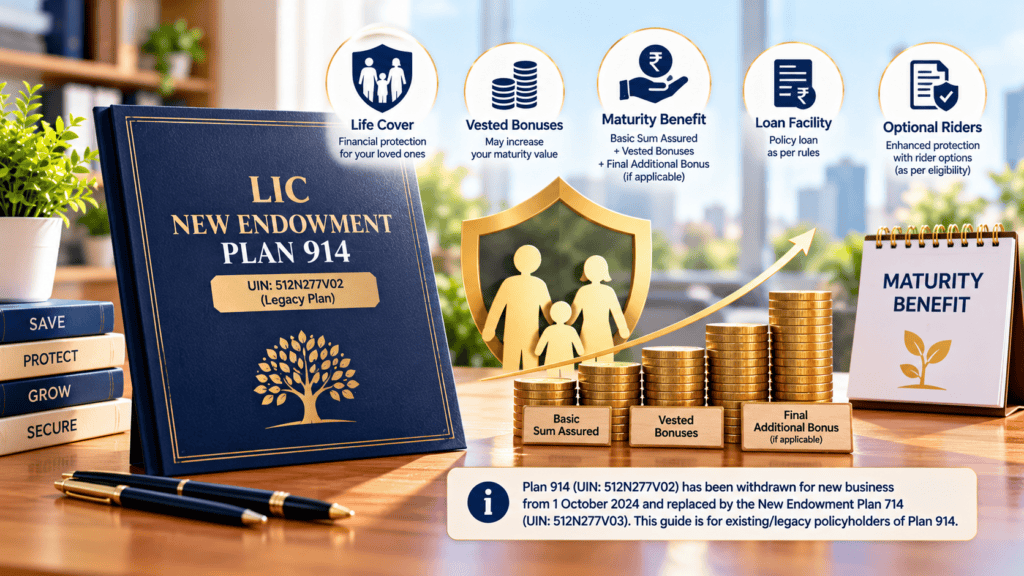
Life cover bundled with savings goals has often made endowment policies popular across India. People looking to secure their family’s future while gradually growing their funds tend to lean toward these. One such option under the lineup is the LIC’s New Endowment Plan 914, which does not tie returns to market performance. Instead, it offers steady protection paired with payouts upon survival to the term. This plan operates as a conventional profit-sharing policy, providing both risk coverage and a lump-sum benefit at maturity.
Unlike with ULIPs, market shifts have no effect here. Benefits are provided through the base coverage amount, along with extras shared by LIC, depending on the company’s financial performance. What lies ahead unpacks the design, traits, advantages, payout at completion, and core points about this plan – clearly laid out so people in India can grasp how it works over the years. The long view matters most.
LIC New Endowment Plan 914 Overview
The LIC New Endowment Plan 914 is designed as an endowment plan that integrates both savings and protection features within a single framework. This plan is involved in nature, indicating that it qualifies for profits if announced by LIC. The plan offers financial security to the family in the event of the policyholder’s death through a death benefit, as well as a maturity benefit if the policyholder lives until the end of the policy term. This LIC endowment plan operates independently of the market, ensuring that it offers secure returns.
Latest Update on New Endowment Plan 914 and what it means for Policy Holders
The LIC New Endowment Plan 914 has been withdrawn on 01.10.2024. But existing policyholders need not worry, as they will continue getting the benefits of the policy as specified in the plan.
Eligibility Criteria and Policy Term
The New Endowment plan comes with an eligibility criterion, which you need to be aware of
| Feature | Details |
| Minimum Basic Sum Assured | ₹1,00,000 |
| Maximum Basic Sum Assured | No limit |
| Sum Assured Multiples | In multiples of ₹5,000 |
| Minimum Age at Entry | 8 years (completed) |
| Maximum Age at Entry | 55 years (nearer birthday) |
| Maximum Maturity Age | 75 years (nearer birthday) |
| Minimum Policy Term | 12 years |
| Maximum Policy Term | 35 years |
As you can see, the policy is flexible as per your requirements, and no upper limit on the sum assured makes it suitable for both young people and older individuals.
LIC New Endowment Plan 914 Key Features
There are some key features of the LIC New Endowment Plan 914 that you need to be aware of. These features make the plan stand out among many others.
- Participating Endowment Plan: the LIC New Endowment Plan is a traditional participating endowment plan that allows the policyholder to split profits with the company.
- Free Look-Up Period: During the 15-day free-look period, the insurance buyer can review the terms of the policy and return it if they’re not happy.
- Loan Facility: If at least two full years’ worth of premiums have been paid and the terms and conditions periodically specified by the corporation have been fulfilled, a loan may be obtained under the policy.
- Surrender Value: Only after paying all required premiums for a minimum of two years can the policy be surrendered. Depending on which is greater, LIC may pay the policyholder the “Special Surrender Value” or the “Guaranteed Surrender Value.”
- Paid-Up Value: The policy will be converted to a paid-up policy if less than two years’ worth of premiums are paid and any subsequent premiums are not paid on time.
- Grace Period: From the date of the first unpaid premium, there will be a grace period of 15 days for monthly premiums and 30 days for yearly, half-yearly, or quarterly premiums.
Premium Payment Structure
LIC New Endowment Plan 914 has a premium payment structure which is made keeping the policyholder in mind. The instalments can be paid in advance at yearly, half-yearly, quarterly, or monthly intervals, depending on the payment method chosen. The minimum instalment amount for each mode of payment is as follows:
| Mode of Instalment Payment | Minimum Instalment Amount |
| Monthly | ₹5,000 |
| Quarterly | ₹15,000 |
| Half-Yearly | ₹25,000 |
| Yearly | ₹50,000 |
Death Benefit Under the Plan
If the person insured passes away while the policy is active, the nominee receives financial support through the LIC New Endowment Plan 914. The death benefit payable in the event that the Life Assured passes away during the policy term, provided the policy is still in effect, will be “Sum Assured on Death.” “Sum Assured on Death” is defined as the greater of seven times the annualised premium or the Basic Sum Assured.
This death benefit must equal at least 105% of the total premiums paid up to the death date. Taxes, additional premiums, and any rider premiums are not included in the premiums mentioned above.
Maturity Benefits and Returns
If the life assured survives for the entirety of the policy, they get maturity benefits like:
- “Sum Assured on Maturity”
- Vested Simple Reversionary Bonuses
- Final Additional Bonus (if any)
Keep in mind that “Sum Assured on maturity” and Basic Sum Assured are the same thing.
Key Bonus Details & Structure
There are several bonuses that are available with the LIC New Endowment Plan 914, and you must know about the bonus structure to see if it’s applicable.
Here are the Bonus Rates (Per 1000/- Sum Assured) in the last 5 years
| Sum Assured Category | Policy Term | 2020–21 | 2019–20 | 2018–19 | 2017–18 | 2016–17 |
| ≤ ₹1 Lakh | 12–15 years | 34 | 34 | 38 | 38 | 38 |
| ≤ ₹1 Lakh | 16–20 years | 38 | 38 | 42 | 42 | 42 |
| ≤ ₹1 Lakh | More than 20 years | 44 | 44 | 48 | 48 | 48 |
| > ₹1 Lakh | 12–15 years | 35 | 35 | 38 | 38 | 38 |
| > ₹1 Lakh | 16–20 years | 39 | 39 | 42 | 42 | 42 |
| > ₹1 Lakh | More than 20 years | 45 | 45 | 48 | 48 | 48 |
According to the above table, if you select a 12-year policy term and your sum assured is Rs. 3 lakhs, LIC will add Rs. 35 as a bonus for each Rs. 1000 of the sum assured. The total bonus amount for Rs. 3 lakhs is 35 x (3,00,000/1000) = Rs. 10,500. The bonus will total Rs. 1,26,000 over a 12-year period.
Loan And Surrender Rules
Policyholders can borrow money and give up their LIC New Endowment Plan 914 policy after paying premiums for at least two full years. Let us take a look at the loan and surrender rules.
LIC New Endowment Plan 914 Rules for Surrender
The rules for surrendering the LIC New Endowment Plan 914 are as follows:
| Aspect | Details |
| Eligibility | Policy can be surrendered after at least 2 full years of premium payment |
| Surrender Value Paid | Higher of Guaranteed Surrender Value (GSV) or Special Surrender Value (SSV) |
| GSV Formula | Total premiums paid (excluding taxes, extra premiums, rider premiums) × applicable GSV factors |
| SSV Calculation | Based on the discounted projected maturity value, including vested bonuses |
| Vested Bonus | The value of vested simple reversionary bonuses is also paid |
LIC New Endowment Plan 914 Loan Rules
The rules for getting a loan on the LIC New Endowment Plan 914 are as follows:
| Aspect | Details |
| Eligibility | Loan available once policy acquires surrender value (after ~2 years of premiums) |
| Loan Amount | In-force: Up to 90% of surrender value. Paid-up: Up to 80% of surrender value |
| Interest Rates | Interest must be paid on time; rates are set by LIC from time to time |
| Termination | Unpaid loan + interest may be deducted from the maturity or death claim |
Tax Benefits of LIC New Endowment Plan 914
The LIC Endowment Plan 914 provides significant tax benefits, which you can take advantage of, such as:
- Premium Deduction (Section 80C): You can get a deduction of upto ₹1.5 Lakh under Section 80C of the Income Tax Act.
- Tax-Free Maturity/Death Benefit (Section 10(10D)): The death benefit or maturity amount (sum assured plus bonuses) that the nominee gets is completely tax-free.
Pros and Cons of LIC New Endowment 914
Just like any policy, there are pros and cons of the LIC New Endowment 914 that you need to know:
| Pros | Cons |
| Safe plan with guaranteed returns and yearly bonuses | Lower returns (typically 4–6%) compared to other investments |
| Provides a death benefit with sum assured + bonuses | May not beat long-term inflation |
| Tax benefits under Section 80C and 10(10D) | Lock-in period; surrender value only after ~3 years |
| Loan facility available after the policy acquires surrender value | Limited flexibility due to fixed premium terms |
| Optional riders for accident, disability, and critical illness |
Suitability of the Plan
LIC New Endowment Plan 914 could fit people drawn to steady payouts from conventional life policies while setting aside money over many years. Not uncommon among folks valuing safety of principal along with a death benefit, instead of chasing riskier investment outcomes that might bring more, might not.
Frequently Asked Questions
Q1. Does the LIC New Endowment Plan 914 Offer Guaranteed Returns?
Yes, the plans offer guaranteed returns, though bonuses aren’t always guaranteed.
Q2. Can I Stop Premium Payments Early?
If you stop paying the premium, the policy will lapse, and you will have to renew it.
Q3. Are maturity proceeds taxable?
Paid-out sums at maturity might escape taxes if the rules in the Income Tax Act apply and policy terms are followed. When conditions line up, what you receive could stay outside taxable income.
Q4. Can you get a loan through this policy?
LIC lets you take loans after the policy builds cash value, if its rules allow it, along with set interest charges.
Q5. Who should consider this plan?
If you’re looking for life cover along with steady savings over time, the LIC New Endowment Plan 914 could fit. It offers fixed returns, not tied to market swings. People who prefer predictability might find it suits their needs. This plan builds value slowly, year after year. Protection plus saving in one setup – without stock market risk. For those eyeing a traditional approach, it stands as an option worth noting.