

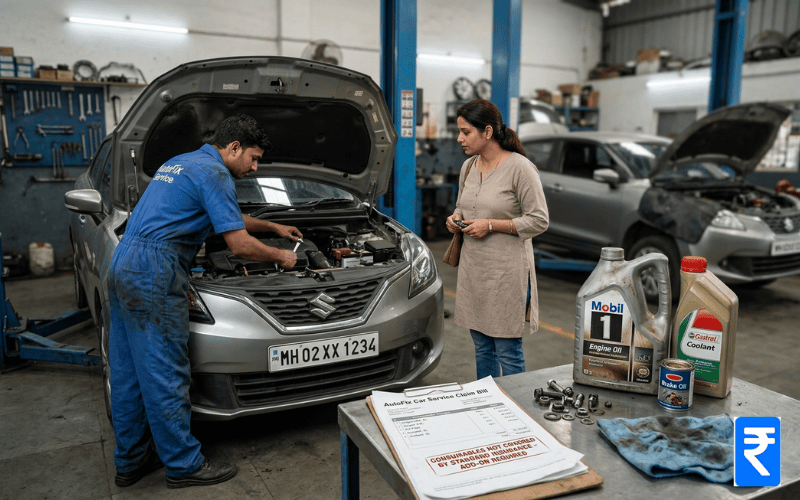
Car repair costs in India have increased because of inflation, advanced vehicle technology, and higher labour charges. Modern cars rely on precise engineering, specialised fluids, and manufacturer-specific components. Even minor accidents can result in repair bills that include several small items beyond major parts and labour. Many of these smaller items are essential but cannot be reused. These are known as consumables.
Most vehicle owners understand basic comprehensive insurance, but may not fully understand how consumables in car insurance work. Standard insurance policies usually exclude consumables, which means policyholders must pay for them during repairs. To address this gap, insurers offer consumables coverage as an add-on. This article explains what consumables are, why they are excluded, what consumables coverage includes, how claims work, the costs involved, and when this add-on may be relevant.
What are Consumables in Car Insurance and Why They Exist
Consumables are materials used during vehicle repairs that cannot be reused once removed or applied. They are necessary to restore the vehicle to a safe and functional condition after an accident.
Understanding consumables in car insurance requires distinguishing consumables from permanent spare parts. Spare parts, such as bumpers or engines, are durable components. Consumables, on the other hand, are fluids, fasteners, and repair materials that get used up during repair.
Definition of Consumables in Insurance Terms
In motor insurance, consumables refer specifically to items required during accident-related repairs. These materials are consumed during the repair process and must be replaced to ensure safety and proper functioning.
Insurance companies treat consumables differently because:
- They cannot be reused after removal or application
- They are used in almost every repair
- They are also part of routine maintenance, not just accident repairs
Because of this, they are typically excluded from standard coverage unless a consumables add-on is selected.
Examples of Consumables Used in Car Repairs
Common examples of consumables in car insurance claims include:
- Engine oil
- Brake fluid
- Coolant
- Gearbox oil
- Power steering fluid
- Nuts, bolts, screws, and washers
- Grease and lubricants
- Sealants and adhesives
- AC refrigerant gas
- Oil and fuel filters
Each of these plays a specific role in ensuring vehicle systems function properly after repairs.
Why Consumables Increase Repair Costs
Consumables may seem inexpensive individually, but their combined cost can be high. According to motor insurance claim data from insurers and industry estimates referenced in policy documents, consumables can account for approximately 5% to 12% of total repair costs in accident claims.
For example:
| Repair Component | Approximate Cost |
| Major parts replacement | ₹20,000 |
| Labor charges | ₹6,000 |
| Consumables | ₹2,500 |
| Total repair cost | ₹28,500 |
Without consumables coverage, the ₹2,500 must be paid by the vehicle owner.
Why Standard Comprehensive Car Insurance Does Not Cover Consumables
Standard comprehensive insurance is designed to cover sudden and accidental damage. Consumables are excluded because insurers classify them as maintenance-related materials. Understanding this exclusion helps clarify the role of consumables in car insurance policies.
How Comprehensive Insurance Coverage is Structured
Comprehensive insurance typically includes:
- Own damage coverage (accident damage to your car)
- Third-party liability coverage
- Theft protection
- Natural disaster damage
However, policy wordings issued under guidelines from the Insurance Regulatory and Development Authority of India (IRDAI) clearly specify exclusions, including consumables.
Insurance Risk Principles Behind Exclusions
Insurance operates on the principle of covering unexpected losses. Consumables are excluded because:
- They are used during regular servicing
- They naturally degrade over time
- Including them in standard policies would increase premiums for all policyholders
By offering consumables coverage as an add-on, insurers allow policyholders to choose additional protection if needed.
Example Showing Financial Impact
Consider an accident repair scenario. Here’s an estimate of what you’re looking at (P.S.: This is merely an example meant to explain things better):
| Expense Category | Covered without an add-on | Covered with an add-on |
| Spare parts | Yes | Yes |
| Labor charges | Yes | Yes |
| Engine oil replacement | No | Yes |
| Coolant refill | No | Yes |
| Fasteners and sealants | No | Yes |
| Out-of-pocket expense | Higher | Lower |
What Consumables Add-On Coverage Includes
Consumables add-on coverage reimburses the cost of consumables used during accident repairs. It applies only when the damage is covered under the policy. This add-on ensures that essential materials required to complete repairs are covered by the insurer.
Fluids and Lubricants Covered
Fluids are among the most common consumables covered. These fluids often must be drained and replaced during accident repairs. These include:
- Engine oil, which lubricates engine components
- Coolant, which prevents engine overheating
- Brake fluid, which ensures braking efficiency
- Gearbox oil, required for transmission operation
- Power steering fluid, which supports the steering function
Repair Materials and Fastening Components are Covered
Small repair materials play an important role in restoring structural stability. Without replacing these consumables, repairs cannot be completed safely. Examples include:
- Nuts and bolts used to secure the replaced parts
- Washers and clips used for alignment
- Adhesives used to bond components
- Sealants are used to prevent leaks
- Lubricants used during assembly
Additional Consumables are Covered by Some Insurers
Some insurers may also cover. However, be warned, coverage lists vary slightly depending on policy wording. Always review the policy document to understand what is included.
- AC refrigerant gas
- Distilled water
- Certain filters
- Grease and protective coatings
What Consumables Coverage Does Not Include
Consumables coverage has specific limitations. It does not cover routine maintenance or wear-and-tear replacements. Understanding exclusions is essential when evaluating consumables in car insurance coverage.
Routine Maintenance Exclusions
Consumables used during regular servicing are not covered. These are considered maintenance expenses.
Examples are:
- Routine engine oil change
- Coolant top-ups
- Scheduled filter replacements
Wear-and-Tear Parts Exclusions
Parts that wear out naturally are excluded. The listed components have predictable lifespans and are not classified as accident consumables.
These include:
- Brake pads
- Tires
- Clutch plates
- Batteries
Claim Eligibility Restrictions
These exclusions follow IRDAI-approved policy guidelines. Consumables coverage does not apply in cases involving:
- Driving without a valid license
- Driving under the influence
- Mechanical breakdown not caused by accidents
- Policy violations
How Consumables Coverage Works During a Claim
The claim process for consumables coverage follows the same steps as standard insurance claims. Understanding how consumables in car insurance claims work helps avoid confusion during repairs.
Step-by-Step Claim Process
The process typically involves:
- Informing the insurer immediately after the accident
- Taking the vehicle to a network garage
- Inspection by an insurance surveyor
- Approval of repair estimate, including consumables
- Completion of repairs
- Settlement of covered costs by the insurer
Cashless vs Reimbursement Claims
Cashless claims are processed at network garages. The insurer pays the garage directly, including consumables if covered. Reimbursement claims require the policyholder to pay first and then submit bills to the insurer.
Documents Required
Common documents include:
- Insurance policy copy
- Registration certificate (RC)
- Driving license
- Repair invoice
- Claim form
Cost of Consumables Add-On and How Premium is Calculated
Consumables add-on coverage is relatively inexpensive compared to overall insurance premiums.
Industry estimates and insurer pricing data indicate that the add-on typically costs 1% to 3% of the own damage premium.
Typical Add-on Cost Ranges in India
| Vehicle Type | Approximate Annual Cost |
| Hatchback | ₹500–₹800 |
| Sedan | ₹700–₹1,200 |
| SUV | ₹900–₹1,500 |
| Premium car | ₹1,200–₹2,000 |
These values vary depending on insurer and vehicle details.
Factors Affecting Add-On Pricing
Several factors influence pricing:
- Vehicle age
- Vehicle model and segment
- Engine capacity
- Repair cost risk
- Insurer underwriting policies
Newer and premium vehicles usually have higher consumables costs.
Cost vs Potential Savings Comparison
If consumables in a repair cost ₹3,000 and the add-on costs ₹800 annually, the add-on may reduce out-of-pocket expenses in accident scenarios.
However, actual financial benefit depends on claim frequency and repair costs.
When Should You Buy a Consumables Add-On?
You may consider it if:
- You own a new car
- You drive frequently
- Your vehicle uses expensive fluids
- You prefer lower out-of-pocket repair costs
It may be less necessary if:
- The car is old
- Repair costs are low
- Premium savings matter more.
Key Benefits and Practical Advantages of Consumables Coverage
Consumables add-on coverage addresses a specific gap in standard insurance policies. Understanding the role of consumables in car insurance helps explain its practical value.
Financial Impact on Repair Expenses
The primary benefit is reducing out-of-pocket expenses during accident repairs. Consumables often add thousands of rupees to repair bills, especially in modern vehicles.
Impact on Cashless Claim Experience
Consumables coverage simplifies cashless claims by reducing the number of excluded items. This can reduce the immediate payments required at repair workshops.
Importance of Modern Vehicles
Modern cars use specialised fluids and manufacturer-specific consumables. These are often more expensive than those used in older vehicles. Consumables coverage helps address these higher costs.
Limitations, Conditions, and Restrictions You Should Know
Consumables add-on coverage has specific eligibility conditions.
Understanding these helps avoid misunderstandings related to consumables in car insurance claims.
- Most insurers offer a consumables add-on only for vehicles less than 5 to 7 years old. Older vehicles may not qualify.
- Some insurers may limit:
- Number of claims per year
- Eligibility based on vehicle condition
- Use of network garages
- Even with consumables coverage, policyholders must pay the compulsory deductible specified in the policy.
Regulatory Framework and Insurance Guidelines in India
Motor insurance add-ons, including consumables coverage, operate within a regulated framework. Here’s an overview:
Role of IRDAI
The Insurance Regulatory and Development Authority of India regulates insurance providers in India. Insurers must clearly disclose add-on coverage terms. It ensures:
- Transparent policy wording
- Standardised claim procedures
- Consumer protection
Policy Transparency Requirements
IRDAI requires insurers to disclose:
- Coverage inclusions
- Exclusions
- Add-on pricing
Claim Dispute Resolution
Consumers can file complaints with insurers or escalate unresolved complaints to IRDAI through the Integrated Grievance Management System (IGMS).
Conclusion
Consumables in your car are absolutely essential. Although they’re a big part of repairing vehicles, they are usually not included in the insurance policy. However, you always have the option to add on.
Consumables in car insurance are useful. They save you from spending a hefty amount later on since there’s no guarantee when an accident may happen. But you do need to know that the general repair is not covered under it. There needs to be a cause and a claim.
Frequently Asked Questions (FAQs)
1. Are consumables always excluded from car insurance?
Yes, consumables are generally excluded from standard comprehensive policies. This includes fluids, sealants, and fasteners used during repairs. However, insurers offer consumables add-on coverage that reimburses these costs if damage occurs due to an accident.
2. How much can consumables add to repair bills?
They can be anywhere around 5% to 12% of the repair total. That mostly depends on how bad the damage is. Say if the total to be paid is ₹30,000, consumables may be around ₹1,500 to ₹3,500. You’ll have to pay it out of your pocket if not added as an add-on.
3. Is consumables add-on coverage mandatory?
No, consumables coverage is optional. Vehicle owners can choose whether to add it to their comprehensive policy. The decision depends on factors such as vehicle age, repair cost risk, and personal financial preference.
4. Does consumables coverage increase insurance premiums significantly?
The cost is small in contrast to the total premium. Add-on insurance is anywhere between ₹500 and ₹2,000 a year. Plus, it also depends on where and who you get your insurance from.
5. Is consumables coverage available for older cars?
Many insurers restrict consumables add-on coverage to vehicles under 5 to 7 years old. Older vehicles may not qualify because of higher maintenance and wear-related risks.